Entry in Your First Speeding Ticket and Insurance
Options After Your First Speeding Ticket to Keep It Off Your Record
Explore legal and administrative steps to resolve a first speeding ticket without it raising your car insurance premium or appearing on your driving record.
By Brandon Lee · Editor
Published
Answer in brief
A first speeding ticket does not guarantee an immediate car insurance rate hike if you take proactive steps before paying the fine. By exploring court deferral agreements, attending approved driver improvement programs, or negotiating an amendment to a non-moving violation, drivers can often keep a clean record and preserve preferred insurance pricing.
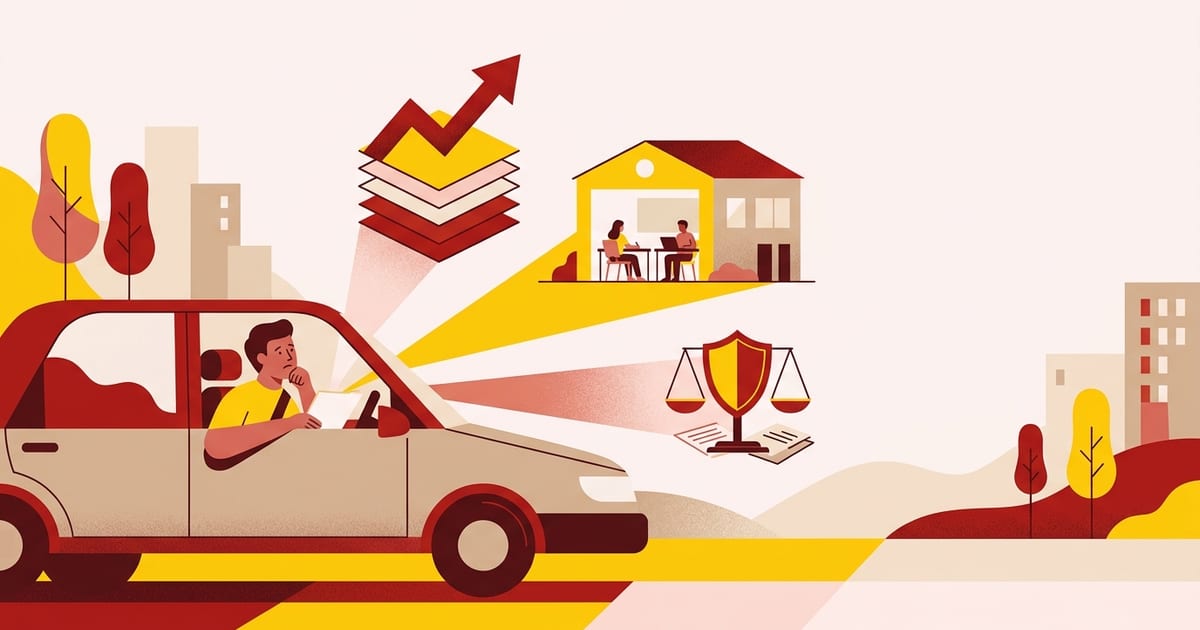
Receiving your first speeding ticket can be unsettling, particularly when calculating the potential impact on your household budget. However, having a previously clean driving history provides significant leverage. Courts and prosecutors are often receptive to alternative resolutions that avoid recording a formal moving violation on your motor vehicle record.
Why You Should Never Simply Pay the Fine Immediately
When a citation is issued, the simplest action appears to be mailing a payment or paying the fee online. However, doing so constitutes an admission of guilt and results in an immediate conviction. Once that conviction is reported to your state licensing agency, it enters public databases that underwriters routinely inspect.
Automobile insurance pricing relies heavily on actuarial risk assessments. The Insurance Information Institute outlines that an individual's driving history is one of the most critical factors in rate calculation. A moving violation signals elevated risk, prompting underwriters to add a surcharge at policy renewal. By resolving the citation through diversion or reclassification, you keep your driving profile clean.
Strategic Pathways to Keep a First Ticket Off Your Record
Depending on your jurisdiction and how fast you were driving, several procedural mechanisms may be available to resolve your citation without an adverse insurance entry.
| Option | How It Works | Record Outcome | Impact on Premium |
|---|---|---|---|
| Deferred Disposition / Probation | Plead no contest, pay fee, maintain clean record for 60–180 days | Dismissed upon completion | Zero insurance impact |
| Court Diversion / Traffic School | Complete an approved defensive driving course | Citation masked or dismissed | Zero insurance impact |
| Plea to Non-Moving Violation | Negotiate to reduce charge to parking or equipment defect | Recorded as non-moving | Zero moving violation surcharge |
| Contesting in Court | Challenge calibration, signage, or crash report details | Dismissed if successful | Zero insurance impact |
Negotiating a Reduction to a Non-Moving Violation
In many local municipal courts, prosecutors or hearing officers possess the discretion to amend charges for individuals with spotless records. A common strategy involves requesting an amendment from speeding to a non-moving violation, such as an improper equipment citation or a parking violation.
While the municipal fine for an amended infraction might match or slightly exceed the original citation amount, the insurance savings are substantial. Insurers track moving violations because studies, like those from the Insurance Institute for Highway Safety, demonstrate a direct link between vehicle speed and crash severity. Non-moving violations, conversely, do not carry underwriting surcharges or insurer points.
How to Request Deferred Adjudication or Court Diversion
If you elect to handle the citation yourself, follow these standard procedural steps to pursue a dismissal through deferral or defensive driving.
- 1
Review Your Appearance Date and Options
Examine the citation for information regarding defensive driving requests or administrative deferral programs. Many courts provide explicit instructions on the back of the ticket.
- 2
Contact the Court Clerk Before the Deadline
Inquire whether the court offers deferred adjudication or pre-trial diversion for first-time offenders. Requesting this option must occur before the appearance date listed on the citation.
- 3
Submit Required Documentation and Court Costs
Complete the court's application, provide a copy of your clean driving record if required, and pay the court administrative costs.
- 4
Complete the Probationary Window or Course
Fulfill all requirements, such as maintaining a violation-free driving record for 90 to 180 days or submitting a certificate from a state-certified driving course.
What to Do If the Ticket Becomes a Conviction
If you miss a court deadline or are ineligible for diversion, the citation will be recorded on your driving history. In that scenario, your rate may stay flat until your next policy renewal date, which is when and how your insurer finds out. Underwriters pull your official driving record periodically rather than monitoring daily court logs.
When the renewal notice arrives with an adjusted premium, shopping the market is the most effective recourse. Data from the National Association of Insurance Commissioners shows that the countrywide average expenditure for auto coverage was $1,281 in 2023. Surcharge algorithms differ dramatically between companies; while one insurer might increase rates significantly for a single minor ticket, another carrier may offer first-accident or minor-ticket forgiveness.
Questions & answers
Will my insurance go up immediately if I get a ticket?
No. Insurers do not monitor driving records in real time. Any premium increase will only occur upon policy renewal, and only if the insurer pulls your updated driving record and discovers an official conviction.
Is it worth hiring an attorney for a first speeding ticket?
For minor infractions, many courts allow drivers to request diversion or traffic school directly through the court clerk without legal representation. However, for severe speeding infractions or jurisdictions with complex court rules, an attorney may help negotiate the charge down to a non-moving violation.
What happens if I just pay the ticket online?
Paying the ticket online without requesting a diversion program is an admission of guilt. The court enters a conviction on your record, points may be assessed by your state licensing agency, and the moving violation will become visible to your insurer upon future record checks.
How long will a first speeding ticket affect my insurance?
If recorded as a conviction, a speeding ticket typically influences insurance pricing for three to five years, corresponding to the insurer's underwriting lookback period, with the largest surcharge applied during the first 12 to 36 months.
Terms: Moving violation, Motor vehicle record (MVR), Non-moving violation, Surcharge, Premium
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Va. Code § 46.2-472 — minimum liability limits — Virginia Law (LIS), Va. Code § 46.2-472Primary lawFor policies effective on/after 1 Jan 2025: $50,000 per person / $100,000 per accident bodily injury / $25,000 property damage.
- Speed — Insurance Institute for Highway SafetyIndependent researchHow speed raises crash likelihood and severity; speed-limit and enforcement research.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.