Entry in How Much Car Insurance Goes Up After a Speeding Ticket
How Insurers Calculate Speeding Ticket Surcharges
Learn how auto insurers calculate rate surcharges after a speeding ticket, which rating factors compound costs, and how to lower your overall premium.
By Brandon Lee · Editor
Published
Answer in brief
Car insurers calculate speeding ticket surcharges by applying an actuarial percentage increase to your baseline risk profile rather than assessing a flat monetary fee. This calculation weighs the violation's severity alongside personal rating variables like age, credit-based insurance scores, and territory, meaning the final dollar increase varies significantly by driver.
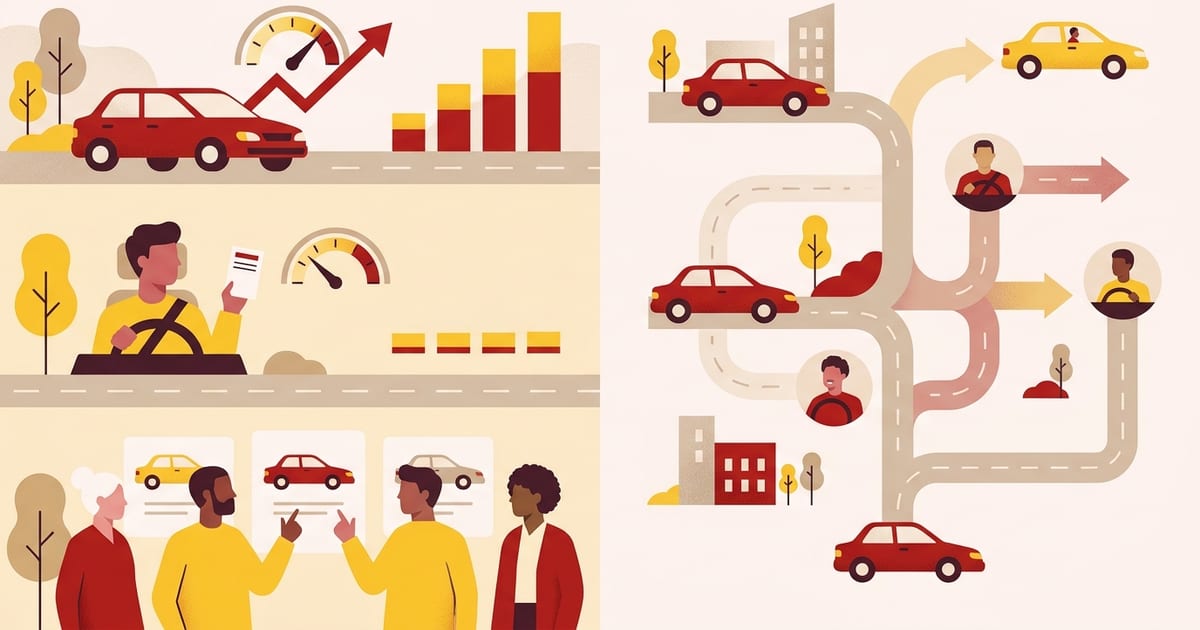
When you receive a citation for driving over the posted limit, your car insurance company does not simply bill you an arbitrary flat fine. Instead, underwriters apply an actuarial surcharge to your policy's baseline premium. Moving violations serve as statistical indicators of future loss: research from the Insurance Institute for Highway Safety demonstrates that higher travel speeds exponentially increase both the likelihood and physical severity of a crash. Because speed amplifies vehicle kinetic energy and reduces reaction margins, insurance actuarial models correlate speeding convictions directly with heightened claims frequency.
The Core Components of an Insurance Surcharge Calculation
To determine the exact dollar surcharge, an insurer starts with your base premium—the foundational cost calculated for your coverage level before any discounts or violations are factored in. According to the Insurance Information Institute, rating algorithms establish this base premium by analyzing primary criteria: driving history, vehicle type, miles driven, geographical location, age, gender, and credit-based insurance scores. Certain rating factors face statutory restrictions depending on where you reside; for example, the Insurance Information Institute notes that territory rating based on ZIP code is prohibited in California and Michigan, while gender rating is prohibited in seven states. Once your baseline risk tier is established, underwriters multiply that baseline by a predetermined percentage assigned to the specific traffic infraction.
How Underwriters Categorize and Tier Speeding Violations
Not every citation triggers the same percentage increase. Underwriting guidelines divide moving infractions into distinct tiers. A single minor violation—such as traveling 1 to 14 miles per hour over the speed limit—typically draws a smaller percentage increase on your liability and collision coverages. However, an excessive speeding citation or a violation classified as a major violation triggers maximum surcharge tiers or non-standard reassignment. Furthermore, broader economic factors magnify the practical cost of these calculations: the Insurance Information Institute reports that countrywide auto premiums faced severe upward pressure from 2021 through 2024 due to escalating vehicle repair inflation, advanced vehicle sensor technology, and rising crash severity. When an insurer applies a 15% to 30% surcharge against a base premium that has already expanded, the out-of-pocket dollar impact is substantial.
Steps to Counterbalance a Rate Calculation Increase
- 1
Adjust Physical Damage Deductibles
According to the Insurance Information Institute, raising your collision and comprehensive deductible from $200 to $500 can reduce that portion of your premium by 15% to 30%, while increasing it to $1,000 can save 40% or more. This reduction helps neutralize the ticket surcharge.
- 2
Drop Physical Damage on Older Vehicles
The Insurance Information Institute recommends evaluating collision and comprehensive coverage on older automobiles; if an older car is worth less than 10 times the annual physical damage premium, dropping comprehensive and collision can yield immediate savings.
- 3
Complete an Approved Defensive Driving Course
Enrolling in state-sanctioned traffic school can secure an ongoing defensive driving discount or mask conviction points, mitigating the actuarial penalty applied by underwriters.
- 4
Consolidate Policies and Claim Usage Discounts
Maximize policy credits by bundling auto and property coverages, verifying low-mileage commuter ratings, and submitting qualifying academic records for student drivers.
- 5
Request Quotes from Multiple Independent Insurers
The Insurance Information Institute suggests collecting at least three separate quotes. Different carriers assign different weight to speeding infractions, making cross-shopping the most direct way to eliminate punitive surcharges.
Questions & answers
Does every car insurance company calculate speeding ticket surcharges the same way?
No. Each insurance carrier establishes its own proprietary rating formula filed with state insurance regulators. While one insurer might raise rates by 10% for a minor speeding ticket, another carrier might impose a 25% surcharge for the same conviction.
Why does a driver's age magnify a speeding ticket surcharge?
Younger drivers exhibit statistically higher crash risks. Insurance Information Institute data documents 42.40 fatal crashes per 100,000 licensed drivers aged 16–20, compared to 21.70 for drivers aged 45–54. Because base premiums are significantly higher for younger demographics, a percentage-based surcharge translates to a much larger dollar increase.
Can increasing my deductible fully offset a speeding ticket rate increase?
In many cases, yes. According to the Insurance Information Institute, increasing collision and comprehensive deductibles from $200 to $1,000 can reduce the physical damage portion of your policy by 40% or more, which frequently offsets the dollar increase generated by a minor speeding citation.
How does a credit-based insurance score affect a speeding surcharge calculation?
Carriers blend your driving record with credit-based insurance scores in states where permitted. Arkansas regulatory data cited by the Insurance Information Institute revealed that credit scoring lowered premiums on approximately 57% of policies while raising them on 23%. Drivers with favorable credit scores often receive smaller net rate increases following an infraction.
Terms: Surcharge, Premium, Lookback period, Minor violation, Defensive driving discount
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Trends and Insights: Auto insurance rates (June 2024) — Insurance Information Institute (2024)Independent researchWhy premiums rose 2021–2024: crash frequency and severity, repair and labour inflation, vehicle technology, attorney involvement.
- Background on: Insurance scoring — Insurance Information InstituteIndependent researchWhat credit-based insurance scores are; Arkansas regulator data showing credit lowered premium on ~57% of auto policies and raised it on ~23%.
- Speed — Insurance Institute for Highway SafetyIndependent researchHow speed raises crash likelihood and severity; speed-limit and enforcement research.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Drivers in fatal motor vehicle crashes by age, 2023 — Insurance Information Institute (2025)Statistical dataFatal-crash involvement per 100,000 licensed drivers: 42.40 (16–20), 35.34 (21–24), 28.97 (25–34), 24.18 (35–44), 21.70 (45–54), 19.45 (55–64), 15.44 (65–74), 16.63 (75+).
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- How to file an auto insurance claim — Insurance Information InstituteConsumer guidanceSteps after a crash: document the scene, notify the insurer promptly, understand the adjuster's role.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.