Entry in Traffic School and Defensive Driving Courses After a Ticket
Can Traffic School Stop an Insurance Increase After a Speeding Ticket?
Learn how completing traffic school or defensive driving can mask a speeding citation, prevent insurer surcharges, and protect your auto insurance rates.
By Chloe Martin · Staff Writer
Published
Answer in brief
Completing an approved traffic school or defensive driving course can often mask a moving violation from your driving record or satisfy court diversion requirements, preventing your insurer from discovering the citation. However, eligibility rules, court approval prerequisites, and state laws dictate whether a course removes the citation completely or simply qualifies you for an optional policy discount.
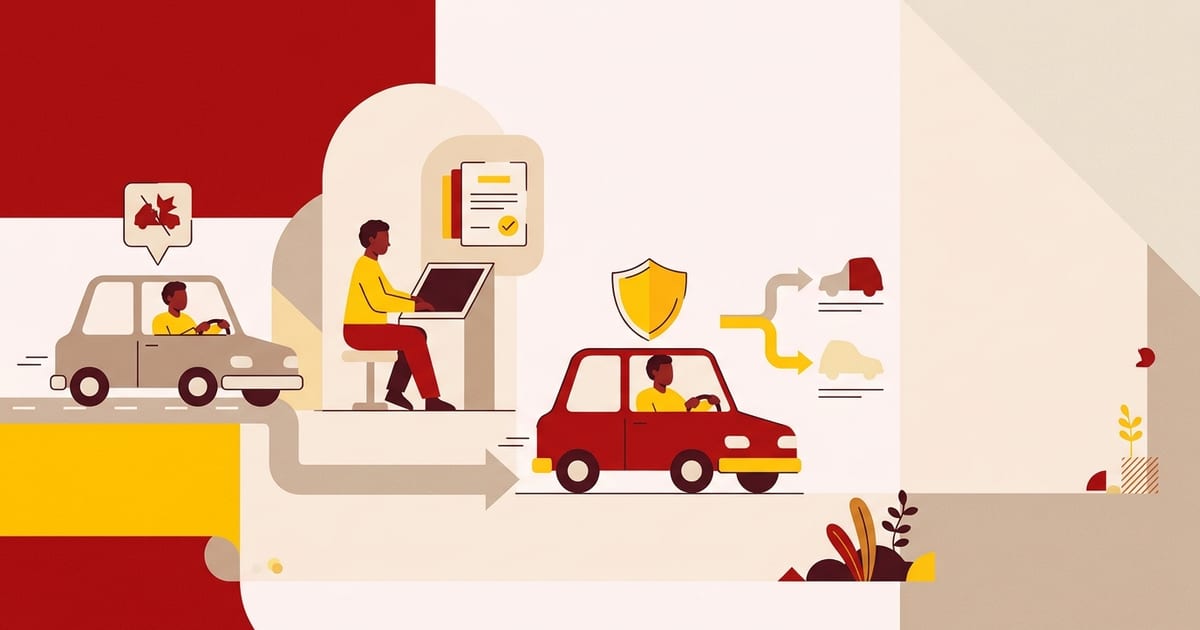
When you receive a citation for driving over the posted limit, the immediate financial worry is rarely just the fine. The lasting expense is often the subsequent insurance surcharge added at renewal. For many drivers, completing an approved course offers a legal pathway to protect their record before their carrier ever learns of the infraction.
How Traffic School Protects Your Policy Premium
The relationship between driver education courses and auto insurance rates depends entirely on whether the course is taken to dismiss a citation through court diversion or completed voluntarily for a premium discount. When used following a citation, the goal is typically conviction masking—keeping the moving violation off your public motor vehicle record.
Car insurance companies calculate risk based on concrete rating factors, including past driving incidents. According to the Insurance Information Institute, pricing evaluates driving records alongside vehicle type, location, mileage, and coverage selections. If an infraction never reaches your official driving history, an underwriter cannot assign insurer points or apply a surcharge to your policy.
Dismissal vs. Point Reduction: What Your Insurer Actually Sees
Not all driver improvement programs function identically across state boundaries. Understanding what your state licensing agency reports to insurance databases determines whether your premium remains stable or experiences an increase.
| Course Resolution Type | Impact on Driving Record | Visible to Insurance? | Impact on Premium |
|---|---|---|---|
| True Citation Dismissal | Ticket is dismissed; no conviction recorded | No | No surcharge applied |
| Conviction Masking / Confidentiality | Citation is recorded but hidden from commercial databases | No | No surcharge applied |
| Administrative Point Reduction | Points removed, but conviction remains visible | Yes | Carrier may still apply moving violation surcharge |
| Voluntary Defensive Driving | Course added to record without citation tie | Yes | May earn a 5% to 10% policy discount |
Step-by-Step: Using Course Completion to Protect Your Rate
You cannot simply sign up for an online course and expect a citation to vanish. Courts enforce strict procedural protocols that must be followed in sequence to ensure the violation is never reported to commercial underwriting databases.
- 1
Verify Court Eligibility
Check your citation paperwork or contact the court clerk. Most jurisdictions prohibit traffic school if you have attended a course within the last 12 to 24 months, were driving a commercial vehicle, or exceeded the limit by excessive speeds.
- 2
Request Court Permission Before Enrolling
Never complete a program independently before receiving formal court approval. Paying your fine online without electing the diversion or traffic school option usually results in an automatic conviction entry on your driving record.
- 3
Choose a State-Approved Provider
Ensure the school is certified by your state licensing agency or the local municipal court. Unaccredited online schools will not be accepted, causing you to miss statutory filing deadlines.
- 4
Submit Proof of Completion Promptly
Submit the certificate of completion and any required administrative fees to the court clerk before the due date, ensuring the dismissal is finalized before your policy renewal date.
What If the Surcharge Is Already Applied?
If you were unable to mask the conviction and an insurer applies a surcharge, completing a voluntary defensive driving discount course may help offset part of the increase. While a defensive driving discount typically yields modest savings on liability and collision coverages, it does not wipe out a major surcharge on its own.
When a moving violation attaches to your file, comparing rates across the broader market becomes essential. According to research from the National Association of Insurance Commissioners, the countrywide average expenditure for auto coverage was $1,281 in 2023, reflecting a 13.98% jump from the prior year. Because individual insurers price moving violations with vastly different risk multipliers, shopping across multiple providers can often mitigate a rate spike.
Additionally, policyholders can adjust physical damage coverages. The Insurance Information Institute notes that raising a collision or comprehensive deductible from $200 to $500 can reduce physical damage costs by 15% to 30%, while opting for a $1,000 deductible can cut those specific costs by 40% or more.
Questions & answers
Does traffic school remove a ticket from my insurance immediately?
Traffic school prevents an insurance increase only if completed through an approved court diversion program before the conviction is reported. If an insurer has already processed the conviction and adjusted your premium, traffic school will not retroactively erase that surcharge unless the court vacates the conviction.
How often can I use traffic school to keep a ticket off my insurance?
Most jurisdictions limit traffic school eligibility to once every 12, 18, or 24 months for moving violations. If you receive a second citation within that restricted timeframe, the violation will generally appear on your driving record and become visible to insurers.
Will a voluntary defensive driving course remove points from an existing ticket?
In most states, a voluntary defensive driving course completed without court authorization cannot dismiss an existing citation or remove court-assessed points. It may, however, qualify you for a standard defensive driving discount on your auto policy.
Do insurers find out if you go to traffic school?
If the court program successfully dismisses or masks the citation, the infraction is shielded from commercial motor vehicle record inquiries, meaning insurers will not see or rate for the incident.
Terms: Conviction masking, Moving violation, Motor vehicle record (MVR), Insurer points, Surcharge
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Speed — Insurance Institute for Highway SafetyIndependent researchHow speed raises crash likelihood and severity; speed-limit and enforcement research.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Facts + Statistics: Highway safety — Insurance Information InstituteStatistical dataCrash, injury and fatality trends used to explain why liability and injury coverages cost what they do.
- Facts + Statistics: Auto insurance — Insurance Information Institute (2025)Statistical dataNAIC countrywide average auto expenditure: $1,127 (2022), $1,282 (2023); most expensive states in 2023 were Florida, Louisiana and New York.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- How to file an auto insurance claim — Insurance Information InstituteConsumer guidanceSteps after a crash: document the scene, notify the insurer promptly, understand the adjuster's role.
- Understanding your insurance deductibles — Insurance Information InstituteConsumer guidanceHow deductibles apply to collision and comprehensive and how raising them lowers premium.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.